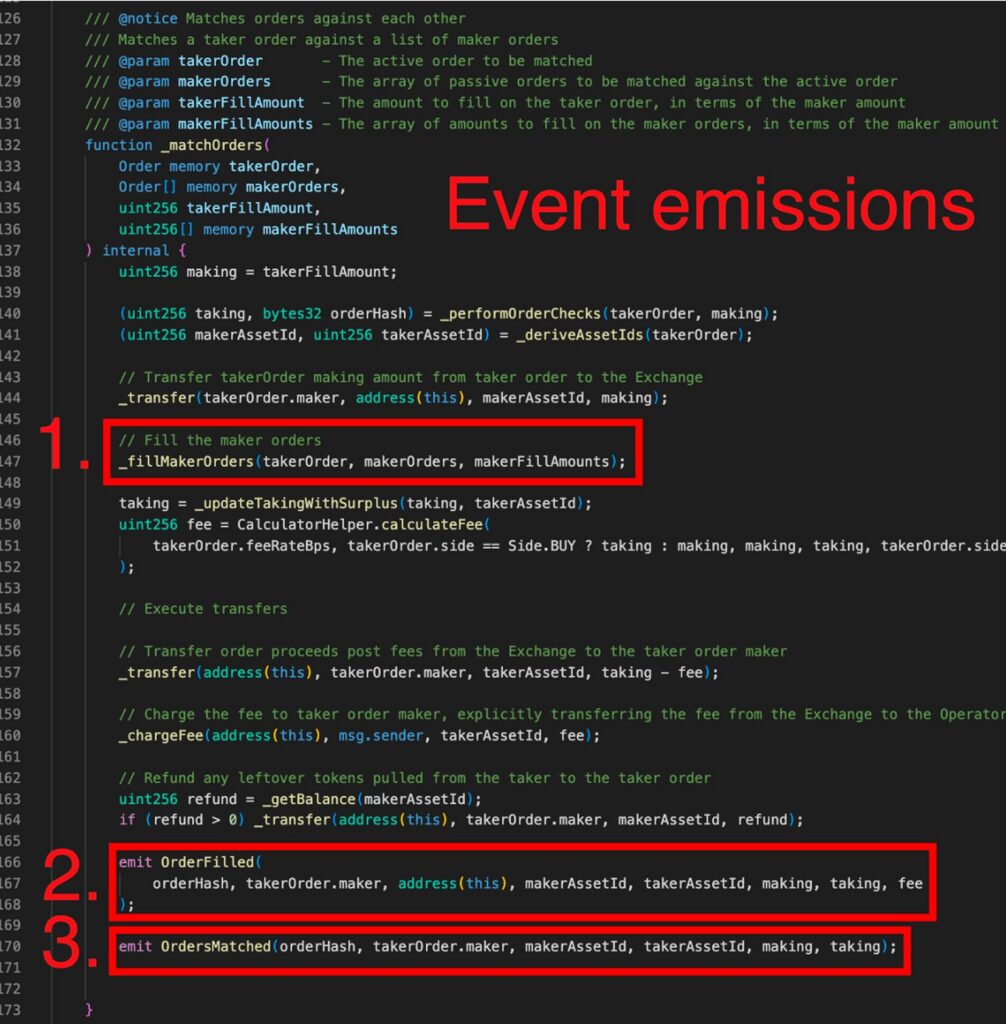
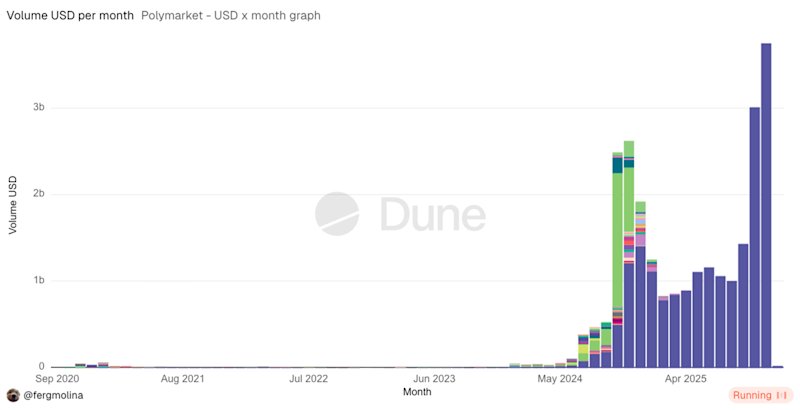
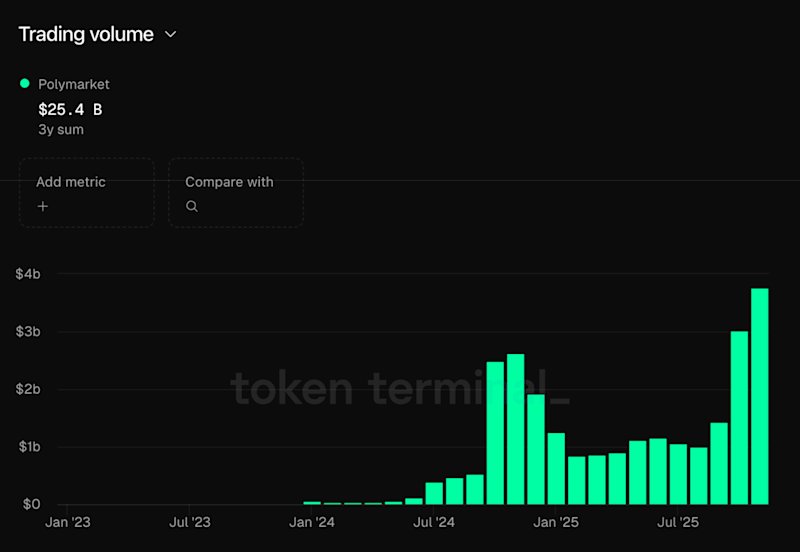
In an analysis published on December 9, 2025, Paradigm argued that a common way of calculating Polymarket trading volume—adding up every onchain OrderFilled event—counts the same trades twice. The issue is not that the events are wrong. It is that Polymarket’s exchange contracts emit separate events describing the maker and taker sides of a match.
One match, two views of the fill
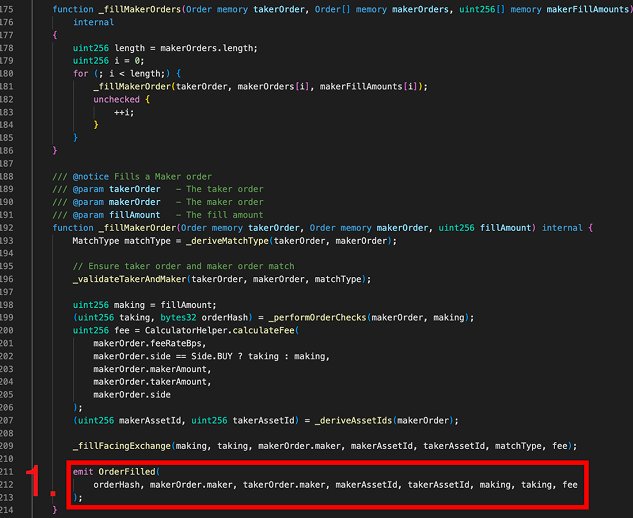
According to Paradigm’s examination of Polymarket’s smart contracts and event data, each trade transaction has one taker and at least one maker. The exchange contract routes the token transfers and emits an OrderFilled event for each maker’s portion of the match. It then emits another OrderFilled event describing the taker’s complete fill, followed by an OrdersMatched event.
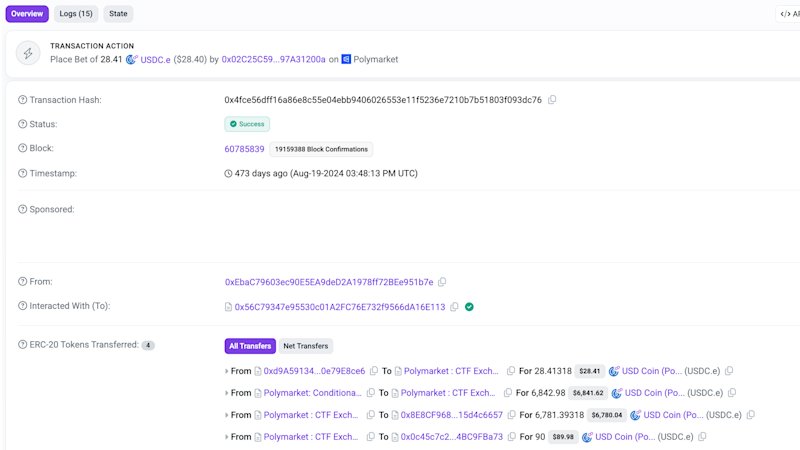
The taker-focused event is another representation of the matched trades, not an additional trade with the exchange contract. Adding it to the maker-focused events therefore inflates the total. Paradigm gives a simple example: a sale of YES tokens for $4.13 appears as $8.26 of volume if both sides’ OrderFilled events are summed.
Why split and merge trades complicate the numbers
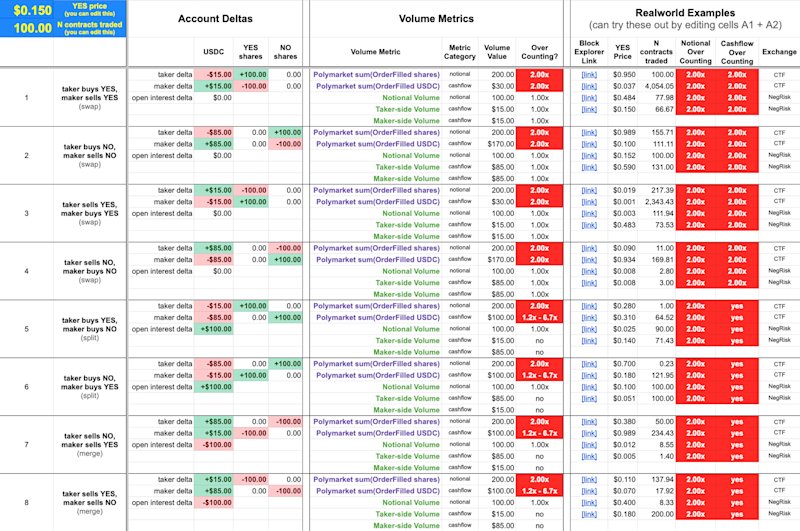
Not every Polymarket match is a conventional swap of shares for USDC. A split exchanges $1 for one YES token and one NO token; a merge exchanges a YES–NO pair for $1. Polymarket can match orders across its YES and NO order books using these operations.
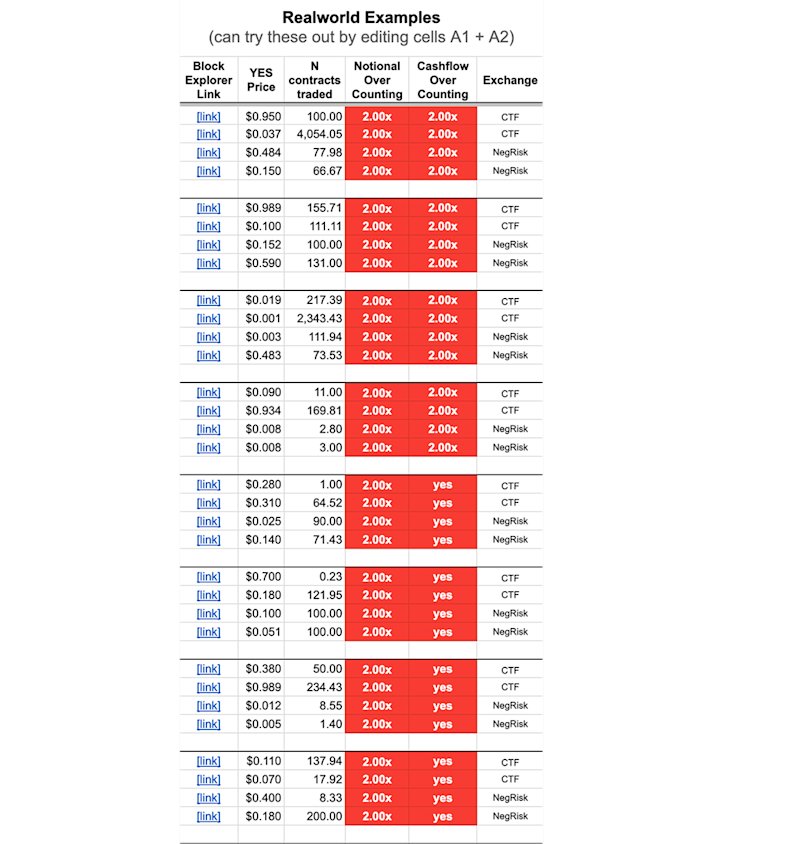
In a split or merge match, the maker and taker can have different USDC cash flows even though they trade the same number of contracts. That makes the choice of cash-flow metric consequential for an individual trade. It does not make adding both sides together a valid one-sided volume measure.
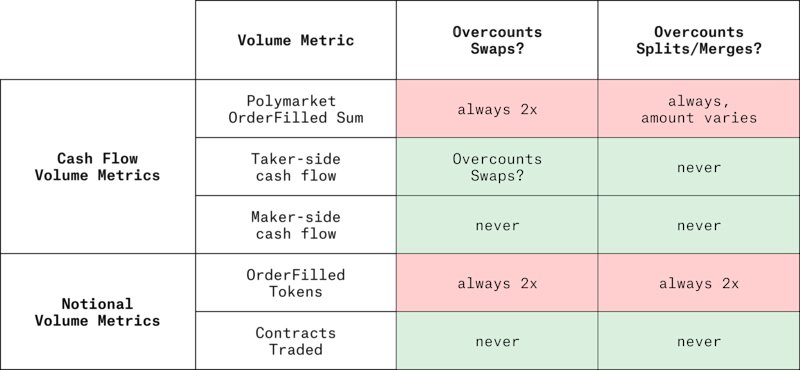
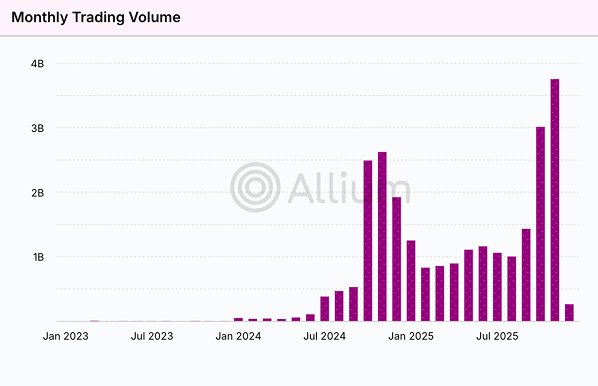
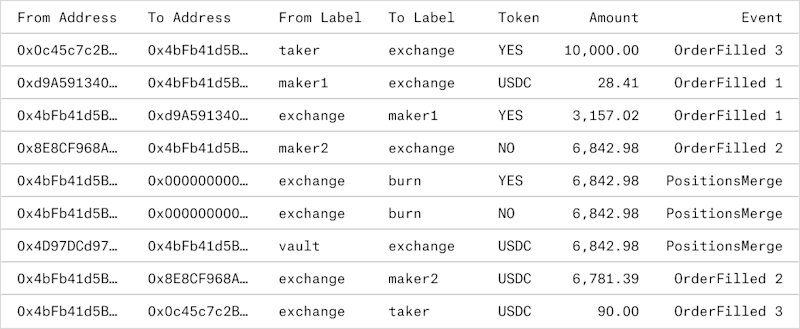
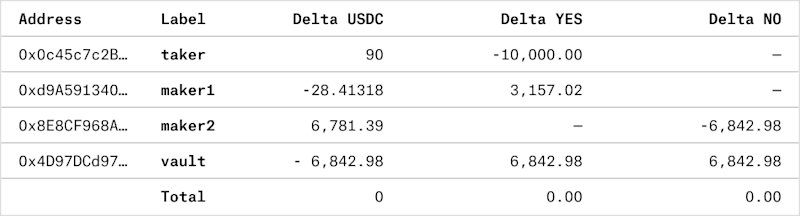
Paradigm’s worked example combines a YES-token swap with a YES–NO merge. Summing its OrderFilled events produces 20,000 contracts and $6,899.80 in USDC volume because it adds the maker and taker records for both legs. The analysis says those sums are not comparable with one-sided volume measures.
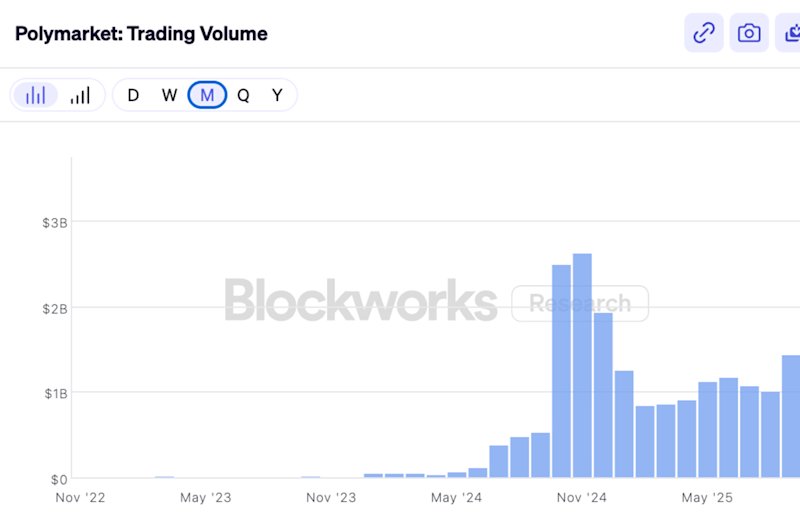
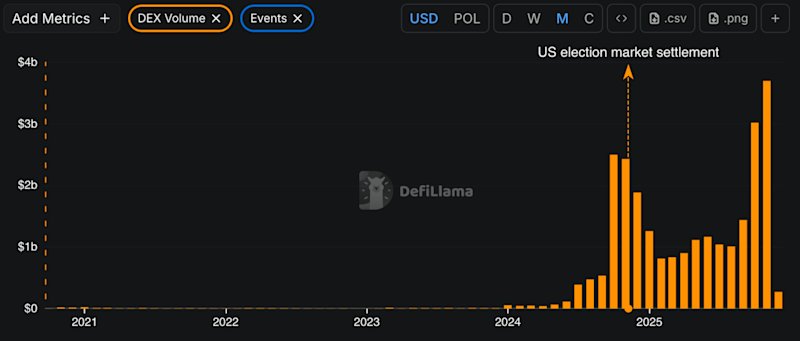
What to count instead
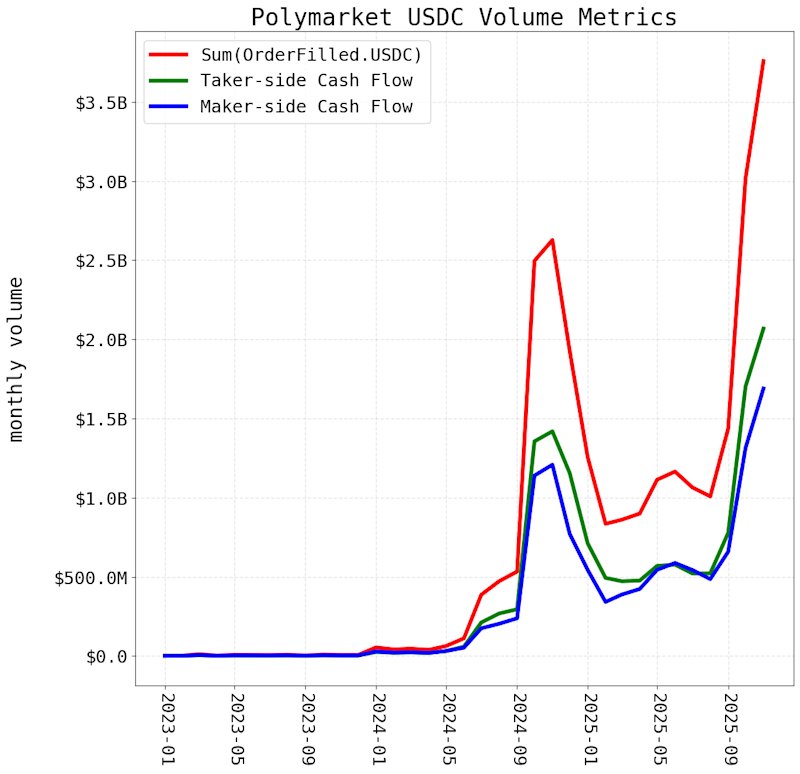
For contract, or notional, volume, Paradigm recommends counting the contracts traded once. For cash-flow volume, it identifies several possible measures, including maker-side cash flow, taker-side cash flow and an average. Its monthly comparison found maker-side, taker-side and share-priced volume each around half the sum of all OrderFilled events; the measures can differ on a single split or merge trade but tend to converge over days or months.
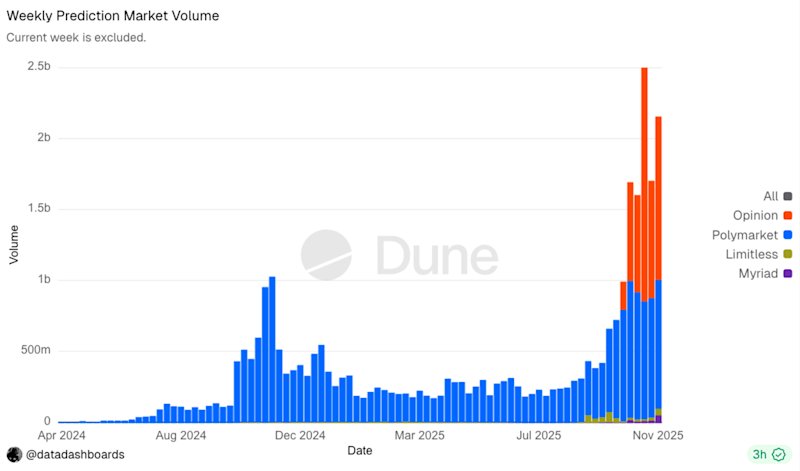
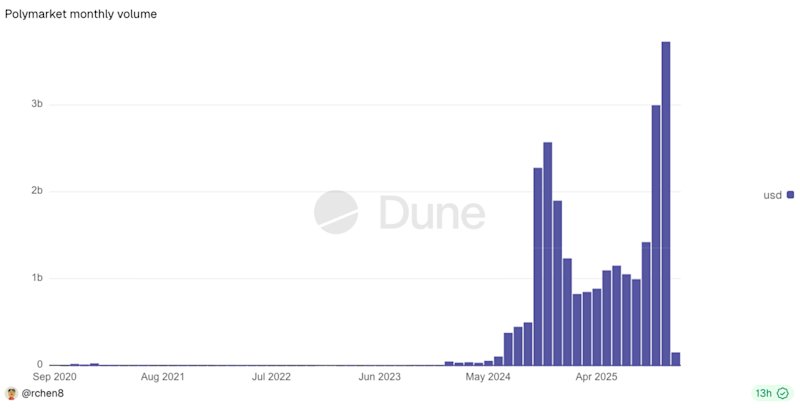
To derive taker-side volume from the events, the analysis says to select OrderFilled records whose taker field is one of Polymarket’s CTF or NegRisk exchange contracts. Selecting records where that field is neither exchange contract yields the maker side. This is a measurement issue, not an allegation that the events contain false data or a finding about wash trading.
Paradigm disclosed that it is an investor in Kalshi, a Polymarket competitor.